Nvidia sinks and pulls Wall Street lower
AI-focused companies and chipmakers face pressure as selling spreads from Wall Street to South Korea and Japan.
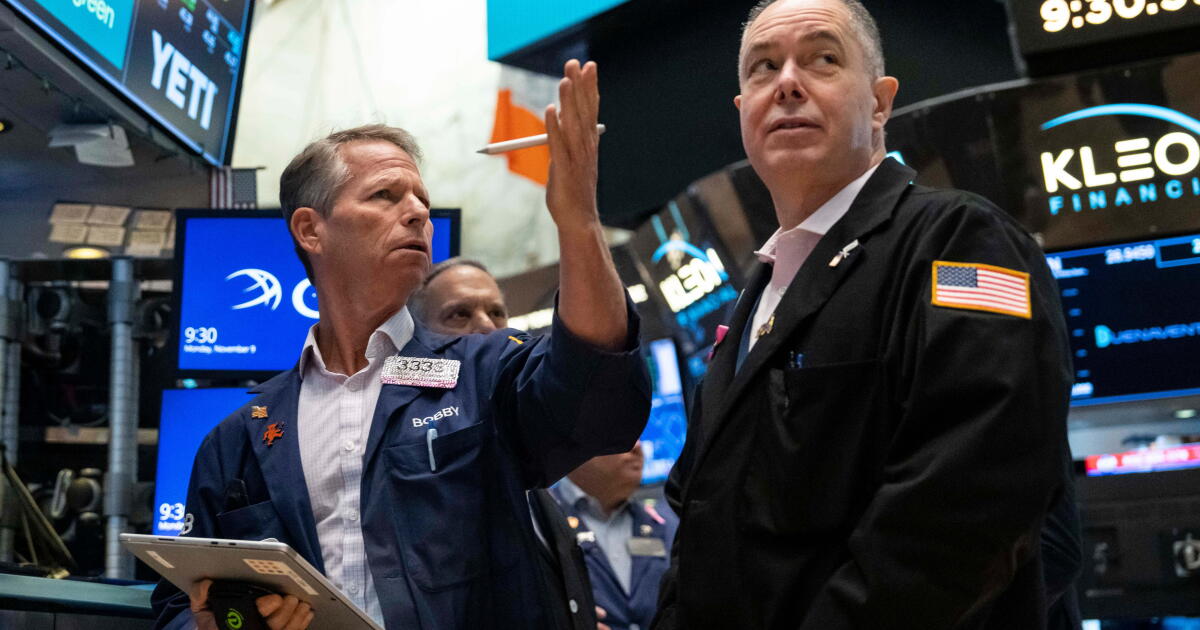
The latest Wall Street sell-off looks less like a market-wide panic than another test of how much artificial intelligence can carry. The Standard & Poor’s 500 index fell 1.9%, the Nasdaq composite lost 2.5%, and Nvidia (NVDA) sank 4.1%, a Los Angeles Times report published Nov. 16 said.
The loss had a lead weight. The Los Angeles Times account from that day said Nvidia was again the heaviest weight on Wall Street, and it said AI-focused companies were by far the biggest weights on the market. That makes the session a concentration problem before it becomes a recession signal or a broad valuation reset.
The selling still reached outside the obvious names. News-Press NOW said the weakness in technology stocks also hit the Dow Jones Industrial Average, which dropped 739 points. A fall in that older benchmark shows that stress in technology can pull money from companies that were not the center of the story.
Nvidia (NVDA) mattered so much because the public accounts identify it as the heaviest single drag, while also saying AI-focused companies were the biggest weights on the market. That is a different claim from ordinary weakness in fast-growing shares. It says the market’s problem began with a group that had become large enough to move the whole tape.
The phrase AI-focused companies also narrows who pays first. Companies tied to the buildout of AI data centres led a brutal sell-off through Wall Street, a Commonwealth Bank account said. If the buildout trade is the source of the pressure, the first damage falls on portfolios crowded into chip suppliers, power-hungry data-centre beneficiaries and funds that lean toward them.
On Thursday, November 5, CNBC-TV18 reported that a sharp sell-off in artificial intelligence and semiconductor shares wiped out gains from the previous session’s post-election rally. The broad benchmark declined 3.3%, the Philadelphia Semiconductor Index (SOX) plunged 11%, and the semiconductor sell-off erased an estimated $2 trillion in market capitalisation, the same report said.
Together, those records suggest the latest fall was not a stray bad session. The selling had already appeared in artificial intelligence and semiconductor shares, and it had already reversed a large part of a rally from the previous session. The newer fall matters because the same kind of exposure was again described as the market’s heaviest weight.
Was This Only a Bad Day?
The cleaner case against the concentration reading is that the loss became broad. Commonwealth Bank said morning gains for the majority of stocks on Wall Street quickly evaporated. That account prevents a neat story in which every falling share is simply an artificial intelligence share in disguise.
Broad selling can start in one crowded trade and still hurt the rest of the market. The Commonwealth Bank account also said the sell-off was led by stocks tied to the buildout of AI data centres. That combination fits a market where one crowded source of gains turns into a source of cash-raising elsewhere.
South Korea and Japan then gave the pressure another route. South Korea’s Kospi tumbled 5.3%, while Japan’s Nikkei 225 sank 1.8% as technology and AI-related stocks fell, Commonwealth Bank said. That makes the exposure global rather than purely a Wall Street problem.
The Ottumwa Courier carried the same account of the S&P and Nasdaq losses that appeared in the Los Angeles Times account, while News-Press NOW carried the Dow move. The repetition does not create another independent cause, but it does show the same market fact being reported across several public accounts: technology weakness drove the day.
A household with a broad index fund felt the fall through the index level, while a Nasdaq-tracking holding was hit harder on those numbers. The practical difference is simple. If the pressure stays concentrated in artificial intelligence and chip shares, a diversified account still loses money, but the pain is heavier in funds tilted toward the companies that led the rally.
A large institution with chip exposure faces a different problem. The Philadelphia Semiconductor Index (SOX) gives that institution a public stress gauge, and the reported market-capitalisation loss shows why forced selling can matter. If clients redeem money or risk limits tighten, the pressure can spread from chipmakers to broader equity books.
A cleaner signal would be daily closes for the Nasdaq composite and the Philadelphia Semiconductor Index (SOX), set beside broader stock benchmarks. If Nasdaq and SOX keep falling while broader indexes slip less, the concentration thesis gains weight. If they recover faster while the broad market keeps falling, the sell-off looks less like an AI-specific unwind.
The next month’s test is therefore narrow. The finding survives only if the public closes keep showing AI and chip exposure under greater pressure than the wider market. A broader decline with recovering chip shares would point to a different sell-off.
What would change it. CNBC TV18 reporting that the S&P 500 fell more sharply than SOX would weaken the case that chip shares are bearing the greater pressure.
Sources
latimes.com Nov. 16newspressnow.com Nov. 16ottumwacourier.com Nov. 16cnbctv18.com Nov. 5commbank.com.au
23 statements, each tied to its sourceWhat each statement rests onHow ARCANE checks a story