Qatar adds North Field carriers while gunfire holes its existing fleet
Doha is buying ships faster than the water they sail has become safe to cross.
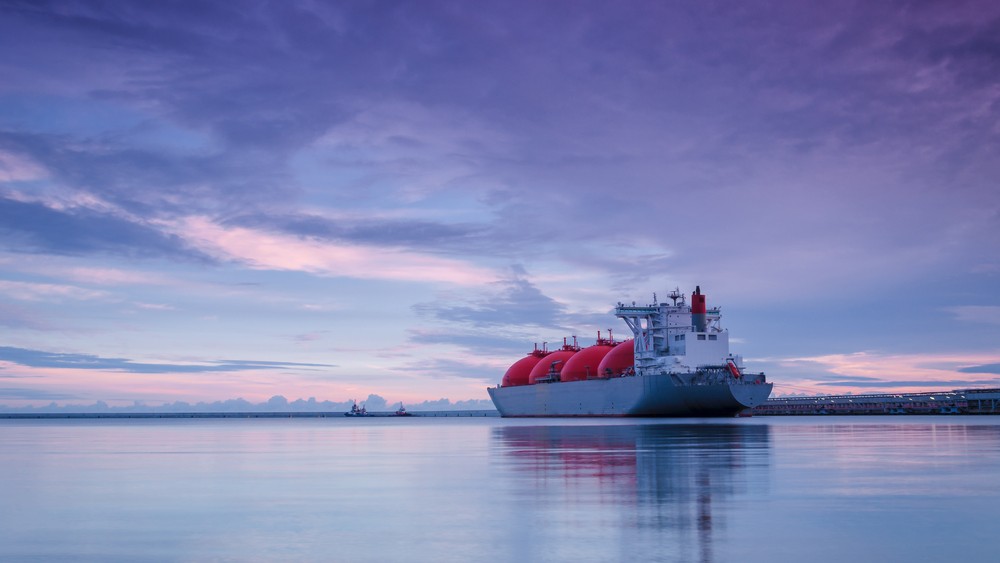
A projectile went through the port side of Al Rekayyat five weeks ago as the tanker left the Strait of Hormuz, leaving Nakilat's ship drifting off Oman with a fire in its engine room and a long wait for salvors. Nakilat confirmed the strike in a statement on July 8, and Al Arabiya reported it the same day.
On August 14, in a Chinese shipyard at Hudong-Zhonghua, Mitsui O.S.K. Lines held the naming ceremony for Al Sabsab; QatarEnergy took delivery three days later, as Ship & Bunker reported on August 19. The new carrier is the fifth of seven MOL ordered in 2022 to haul Qatari gas, and Baird Maritime reported on August 18 that it is the tenth 174,000-cubic-meter vessel the yard has built for QatarEnergy. The same state that cannot yet keep its shipping route whole is adding hulls to it anyway.
QatarEnergy is running the largest shipbuilding program in the industry's history while its main export artery is under fire, and every new hull binds state money to a waterway someone keeps shooting at. The naming ceremony this week was one more hull ticking onto that book.
QatarEnergy, the state producer, is building to move gas from the North Field, the offshore reservoir it is expanding from 77 million tons of annual output toward 110 million tons (QatarEnergy LNG; World Ports, 2026). Nakilat, the Qatari shipping company, owns many of those ships outright and charters them to QatarEnergy on long terms Qatar must pay for even if it cancels; Nakilat laid out those terms in its press release of February 10, 2024.
MOL and the other Japanese and Greek owners take the ships onto their books because a fifteen-year charter from Doha is the closest thing shipping has to a government bond.
The yards, Hudong-Zhonghua in China and Samsung and Hyundai in Korea, collect the money either way.
The arithmetic
Under the program now concluded, QatarEnergy has 128 ships on order, including twenty-four QC-Max giants of 271,000 cubic meters each, the largest gas carriers ever drawn, and it has signaled at least seventy more beyond that (Economy Middle East, 2025; iMarine News quoting QatarEnergy, undated 2026). Each of those big ships cost roughly $333 million, about $8 billion for the batch alone, money committed years before the first cargo moves; iMarine News cited QatarEnergy's own figures in August 2026.
Offshore Industry's June 2026 tally puts the global orderbook for LNG carriers near 350 ships, roughly half the existing fleet of about 700. GTT, the French firm whose containment systems go inside nearly every new hull, had 272 LNG carriers on its own order book at the end of June after signing fifty-six more in the first half of the year, according to its half-year results carried by Xinde Marine News in July 2026. When one buyer's program is half the world's backlog, the buyer sets the price of steel, and everyone else pays what Qatar's appetite made the going rate.
The tanker owners of 1973
The tanker owners of 1973 ran this cycle before. After the oil shock, Western majors chartered everything that floated and owners ordered supertankers by the hundred at record prices. Within a decade, berths sat empty from Norway to Hong Kong and ships built for thirty years of service went to the breakers at ten, because the charters were worth less than the steel when demand flattened and the fleet arrived all at once. The parallel is exact in shape: long commitments signed at the top, deliveries stacked into a narrow window, one customer driving the cycle.
The counter-example argues the other way. In the early 2010s the same doom was forecast for the LNG carrier market, and instead the American shale export wave arrived right on schedule and soaked up every ship for most of a decade. This time the demand side is real too: Europe has rebuilt its import terminals, and Asia keeps signing. If North Field's extra gas actually flows from 2027 onward, these 128 ships are the pipeline rather than excess tonnage. That is the bull case, and QatarEnergy management believes it enough to bet billions of state money on it.
But the analogy bends where risk sits. In the tanker bust it was private Greek and Norwegian owners who drowned. Today, Nakilat holds the ships and the charter obligations sit with a sovereign fund's balance sheet, so the loss, if it comes, lands on Qatar's treasury rather than on leveraged shipping men in Piraeus.
What the private sector does hold is the spot exposure: hundreds of uncommitted carriers outside the Qatari program whose day rates have already sagged as deliveries stack up, with the market described as oversupplied through 2026 by the LNGInsights fleet tracker in August 2026. The state absorbs its own mistake slowly, while the independent owner feels it immediately and completely.
The water itself
There is also the water itself. A projectile struck Al Rekayyat eight nautical miles off Oman while a reported US-Iran understanding to halt attacks on the strait was supposedly in force, and the ship waited weeks for salvage, as Ocean Crew News reported on July 7 and a Climate Intelligence brief noted in July 2026.
Every additional hull Qatar puts on the water is one more asset routed through a chokepoint where insurance premiums, war-risk cover and routing decisions now price in the chance of being shot at. If attacks resume in earnest, the binding constraint on Qatari exports becomes whether underwriters will cover the voyage at any tolerable rate. Steel arrives on schedule, though safety does not obey a delivery calendar.
First, deliveries through 2027 and 2028 flood the market with capacity just as Qatar's own extra gas starts moving, which crushes rates for anyone without a Doha charter behind them. Second, yard prices fall once the Qatari program ends, and whoever orders then, likely Chinese owners expanding their own fleets, buys cheap and inherits the cycle's downside. Third, if the strait stays dangerous, Qatar's fixed-cost fleet becomes a fleet that must sail anyway, because the charter payments come due regardless, so Qatari cargoes keep transiting risk that other suppliers simply route around. The state's commitment converts a security problem into a reason not to stop sailing.
Three things settle the argument over the next quarter. The salvage resolution of Al Rekayyat, the war-risk premium quotes for Hormuz transits, and whether QatarEnergy formally places the promised next batch of seventy-plus orders (iMarine News, 2026). More orders into an oversupplied freight market with a live shooting risk would seal the pattern. A durable US-Iran settlement that collapses war-risk premiums, combined with Asian term contracts landing on schedule from 2027, would make the fleet exactly the floating pipeline Doha says it is.
The people who will absorb this story are the Filipino and Indian crews aboard ships transiting Hormuz, the Korean and Chinese welders whose order books empty when Qatar finishes, and the Qatari treasury holding paper on 128 hulls. The profit in this cycle belongs to the yards and the chartered owners who got paid first; the risk belongs to whoever holds the ships last.
Doha is betting that the last holder will be itself, and that the strait stays open. One of those bets is its choice. The other is Iran's.