Treasury hits forty trillion in debt, then doubles the buybacks hiding it
A borrower that must borrow cannot afford for anyone to notice how much it already owes.
The forty trillion dollar line was crossed on Wednesday. Within hours, Treasury had announced it would double the size of its buyback operations in long bonds, raising the maximum per operation from two billion dollars to at least four billion in the ten-to-twenty-year and twenty-to-thirty-year sectors — Reuters reported the move on August 19.
The government has never owed this much; the BBC noted on August 20 that the debt has doubled inside a decade. On the same day it paid for an operation built to convince markets not to look at the number.
The mechanics are widely misunderstood. In a buyback, Treasury sells brand-new bills and notes and uses the proceeds to purchase older, less-traded bonds off dealers before maturity, swapping one form of debt for another. As the Epoch Times laid out in its August 2026 explainer, the total owed does not fall by a dollar. What changes is which bond sits on which balance sheet, and how easily it can be sold on a bad day.
Treasury has been running these operations since it relaunched the program in May 2024 as a liquidity tool.
The same Epoch Times piece counted close to two hundred billion dollars of debt bought back this fiscal year alone.
The long end stopped cooperating
The long end of the market had turned hostile. The thirty-year Treasury yield touched five point three four percent on August 18, its highest since around 2001, after weeks of steady climb — CoinDesk reported the level on August 22, and an edugate market note dated August 18 caught the print itself. The Economist put it more conservatively in its August 22 edition, noting yields had reached levels last seen in 2007 as investors worried about mounting government debt.
Either way, the direction was unmistakable: the longest-lived loans in the world were getting more expensive exactly as the borrower needed to roll trillions of them. Bessent's announcement knocked the thirty-year yield down roughly fifteen basis points to around five point one nine percent, its largest one-day drop since October 2025, as LinkedIn's Morning Markets noted on August 20 and CoinDesk confirmed on August 22.
Scott Bessent runs the Treasury and wants long-term borrowing costs down without asking Congress for anything, because asking Congress means admitting there is a problem legislation could fix. Bond dealers want the program too, since buybacks hand them a guaranteed exit for old inventory that ties up their capital. Foreign holders, led by Japan and China, want their existing stakes protected from further price erosion; buybacks provide that protection. The Federal Reserve sits apart, holding rates where they are while the fiscal side does the heavy lifting, a division of labor that suits everyone right up until it doesn't (Bloomberg, Aug 19).
The trigger is a few weeks of ugly yield action culminating in a soft long-bond auction and a nineteen-year-high yield print. Underneath sits arithmetic: deficits running near two trillion dollars a year, interest costs that now rival defense spending, and a tax-and-spending settlement both parties have chosen not to change, as the New York Times framed it on August 19. The buyback addresses none of that. It rearranges the shelves so the store looks fuller while the warehouse empties.
One honest precedent
From 2000 to 2002, Treasury bought back its own long bonds under Secretaries Summers and O'Neill, and academic work later confirmed the operations moved prices meaningfully, in a Journal of Financial Economics study of the 2000-2002 buybacks published in November 2024. But read the setting. That program ran during budget surpluses, when the government genuinely had money it did not need and was retiring debt outright. This one runs against record deficits, swapping new debt for old at scale. Then it signaled abundance; now it signals management of scarcity.
Japan's Ministry of Finance spent decades managing its government bond market with purchases, guidance and quiet arm-twisting, and for years it worked, until the yen paid the price in a devaluation spiral that began in earnest in 2022. An economist cited by Fortune this week made exactly that comparison, warning that Bessent is heading down a similar path toward dollar debasement (Fortune, Aug 21). Japan shows the tool can hold yields down for a very long time. It also shows what the currency eventually charges for the service.
Dealers get paid to make markets in old bonds again, and the long end rallies, as it did on the announcement day. Next, mortgage rates and corporate borrowing costs ease off their highs; this is the political payoff Bessent needs before the autumn refunding. If buybacks become the standing answer to every yield spike, the market learns that Treasury will always absorb selling pressure, and holders demand a slightly higher premium anyway for the risk that one day the program hits a limit. That premium lands on every thirty-year mortgage and every utility bond priced off the long end.
Who pays and who profits
The profit side is concentrated. Primary dealers earn spread and fee income on every operation, and funds that bought long bonds at five point three percent just booked an instant markup, as CoinDesk reported on August 22. The payment side is diffuse and delayed. Taxpayers fund the interest on the ever-larger bill stock the swaps create, savers earn whatever the short end pays, and dollar holders everywhere absorb the debasement risk the Fortune piece named. Nobody writes that check this month. It accrues.
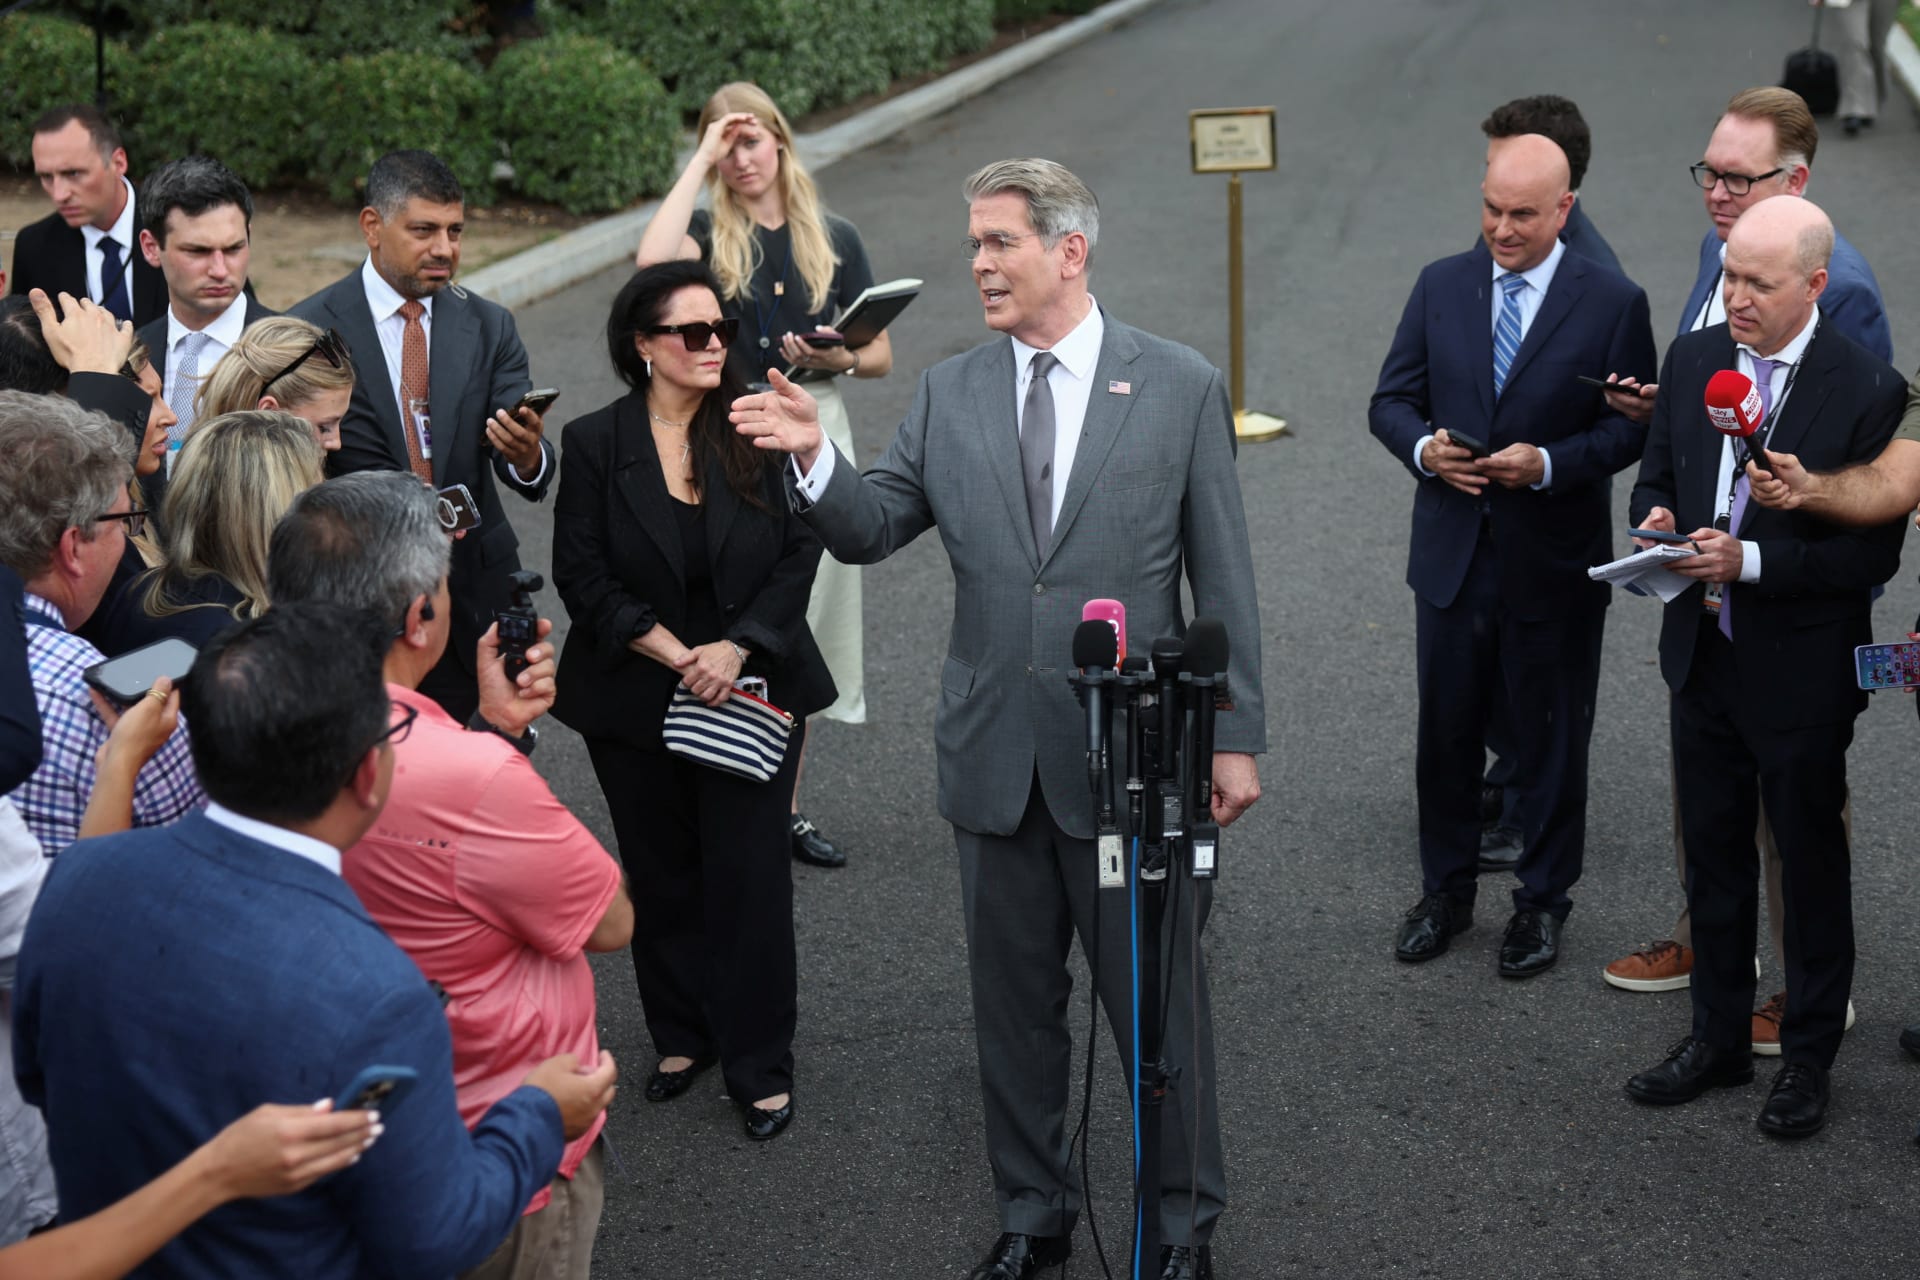
Bessent was asked about the milestone outside the White House on Thursday and said there is nothing magic about the forty trillion number and America can grow its way out, remarks carried in RealClearPolitics video from August 21 and covered by The Hill on August 20.
He also said the four billion cap on buybacks might not be the ceiling, telling reporters the program could grow beyond it and promising a fresh fiscal initiative on borrowing costs, CNBC reported on August 20, with Bloomberg adding its own account the same day. Growth would indeed solve this. So would a buyer who never blinks, which is closer to what the buyback desk actually offers.
The read confirms if the September 9 operation, the first under the doubled cap, clears smoothly and the thirty-year yield holds below five and a quarter into the November refunding, per the Treasury announcement schedule Reuters carried on August 19. It breaks if a long-bond auction fails on the bids despite the support program, or if foreign official accounts trim holdings in the monthly TIC data while the buybacks run. If the biggest lenders start selling into the program built to catch sellers, the desk will have found the edge of its own balance sheet.
A treasury that buys its own bonds when yields rise has stopped being a pure borrower and started being a market manager, and history's lesson about market managers is that they win every battle except the last one. The danger begins the week the buyback becomes load-bearing.