Record cargo is moving through ports where the queue says otherwise
Throughput reports measure what got ashore; the anchorage counts measure everything still stuck outside, and only one of those numbers is lying.
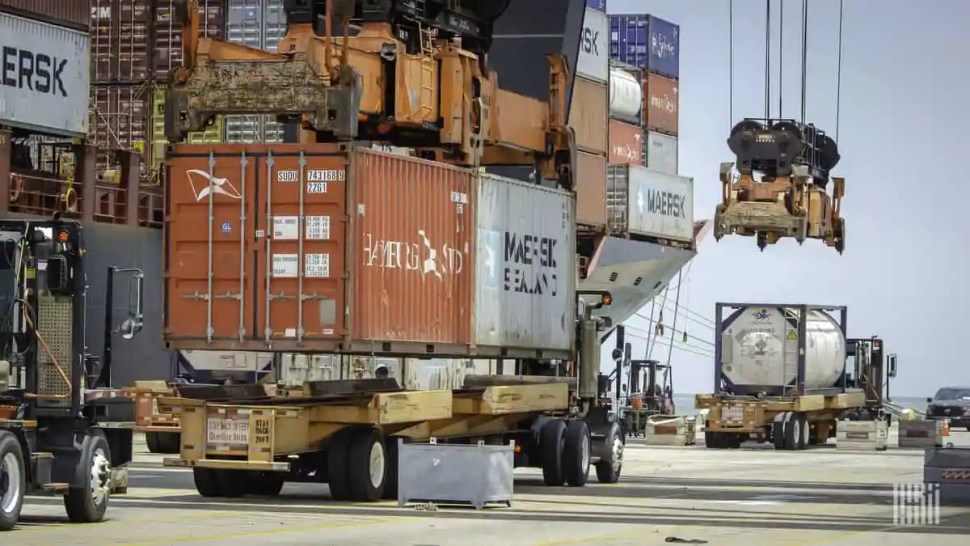
Somewhere on the water right now is a fleet of ships that officially does not exist — about 1.7 million TEU of container capacity, more than Evergreen's whole fleet, stalled in delays. Sea-Intelligence, as reported by The Loadstar on August 19, calculates that congestion is swallowing 5% of global capacity, which is double the pre-pandemic baseline of 2.2%.
Yet the ports themselves are posting victory laps. The Port of Los Angeles moved 960,464 TEUs in July, its second-busiest July on record, and says the average vessel waits about a day, according to ShipUniverse Global Port Watch on August 19. Triumph at the quay, gridlock at anchorage, and both sets of numbers come from the same ocean.
The gap exists because throughput is a lagging scoreboard. A port counts boxes moved across the quay; a shipper lives in the days before that. ShipUniverse Global Port Watch on August 19 reports that at anchor off Conakry the seven-day average wait stands at 19 days, and off Busan, laden-yard utilization at BNCT has climbed above 100%.
When Typhoon Dolphin passed, vessel waits at Shanghai, Ningbo, and Shenzhen stretched as long as 12 days in some cases, according to Worldwide Logistics Group on August 19. A terminal can post a record monthly volume and still be the reason autumn inventory arrives late.
This week’s triggers were loud and separate. Port Technology International reported on August 18 that a 24-hour warning strike across six German gateways — including Hamburg, Bremerhaven and Wilhelmshaven — called by the union ver.di had shut terminals run by HHLA and Eurogate. ShipUniverse, on August 19, wrote that ver.di wants an 8.2% hourly increase or at least €2.50 an hour over twelve months; the employers’ group ZDS is offering 5.1% over nineteen months. Negotiations resume with nothing settled, so the walkouts can repeat. In Asia, the typhoon backlog is draining slowly.
The pressure underneath is architectural. The Loadstar reported on August 19 that Alphaliner’s analysis of the Far East-North Europe trade shows why: MSC’s Swan service spreads roughly 2,500 TEU across each of six European calls, while Evergreen’s CEM service concentrates an average of 7,830 TEU into just three westbound calls using ships averaging 23,490 TEU. Every carrier that consolidated its network onto fewer, bigger ships turned individual port calls into tidal waves.
War, weather and diverted cargo
Add weather — typhoons, drought on river-dependent routes — and a war in the Gulf diverting UAE cargo through Fujairah and Khor Fakkan, where AD Ports’ domestic Q2 container volume fell 65% as traffic shifted, as recorded in the ShipUniverse Global Port Watch of August 19. The queues stop clearing even when the cranes keep working.
The actors want different things and the mismatch drives the story. Carriers like Maersk and Hapag-Lloyd want schedules they can sell; Maersk has publicly singled out congestion as a new and major component of container-market dynamics because stuck ships generate a growing tide of empty containers for ports to process, Freightos reported August 18.
Terminal operators want capital, hence Louisiana’s new international terminal winning its federal construction permit on August 17 and Lyttelton announcing an $821 million expansion in New Zealand, according to ShipUniverse Global Port Watch of the 19th. Dockers want the wage share of a boom year. Shippers just want their boxes. Each party optimises its own number, and the anchorage count is nobody’s number.
The obvious comparison is 2021, when San Pedro Bay filled with drifting ships and American shelves went bare. That year congestion was demand-driven: consumers bought goods, ships chased the cargo, and the cure was demand destruction. This time, demand is softening.
Freightos, on August 18, figures Far East-North Europe spot rates sliding more than $1,000/FEU, about 20%, since the mid-July peak, to roughly $4,700/FEU this week. Yet the capacity-absorption figure has risen. Congestion that survives falling freight rates is not a demand problem; it is a network-and-infrastructure problem, which historically takes years of steel and concrete to fix, not one weak peak season.
Los Angeles is absorbing near-record volume with one-day waits because it invested through the last cycle and kept berth productivity high. The ShipUniverse Global Port Watch of August 19 notes Savannah grew July volume 5.7% to 503,739 TEUs without a crisis. Singapore’s automated Tuas Port crossed 25 million cumulative TEUs since opening in 2022. The system is bifurcating: gateways that expanded get the cargo and the growth, gateways that didn’t get the queue, and the global average quietly worsens even as the best ports set records.
Who profits, who pays
The carriers profit, for now, because 1.7 million TEU of trapped ships works exactly like scrapping a fleet the size of Evergreen’s, tightening effective supply and propping up rates. The Loadstar reported on August 13 that Maersk beat expectations this month, even as volumes cooled.
The payer is the cargo owner — still paying transpacific rates near $7,400/FEU to the West Coast and a fresh high of $9,400/FEU to the East Coast while Europe-bound prices sag, plus bunker costs up 15% since the ceasefire collapse and emergency fuel surcharges of about $90/FEU arriving mid-September, according to Freightos’s August 18 update.
Ports with berths to spare collect the diverted cargo. Ports without collect strikes.
The consequence lands furthest out on inventories. Retailers ordering Christmas freight now face longer effective transit times on lanes they thought were calming down, so they order earlier and bigger, which loads the ports more, which lengthens the queues. That loop is how a congested autumn becomes a congested winter, regardless of what consumer demand does. The German wage deal, whatever it turns out to be, will not release a single anchored ship in Conakry or clear a yard in Busan.
Trust the anchorage, not the annual report. Throughput figures tell you a port survived its own congestion; waiting-time data tell you whether next month's cargo will.
Until the gap between Sea-Intelligence’s 5% absorption and the old 2.2% baseline closes, every record month is being paid for somewhere offshore, in diesel and demurrage, by people whose names never appear in a port authority press release.