CMA CGM holds Panama Canal surcharge after transit capacity returns and before new cuts
Shippers kept paying the increased fee even as normal transits resumed and before later slot reductions affected canal access and draft limits.
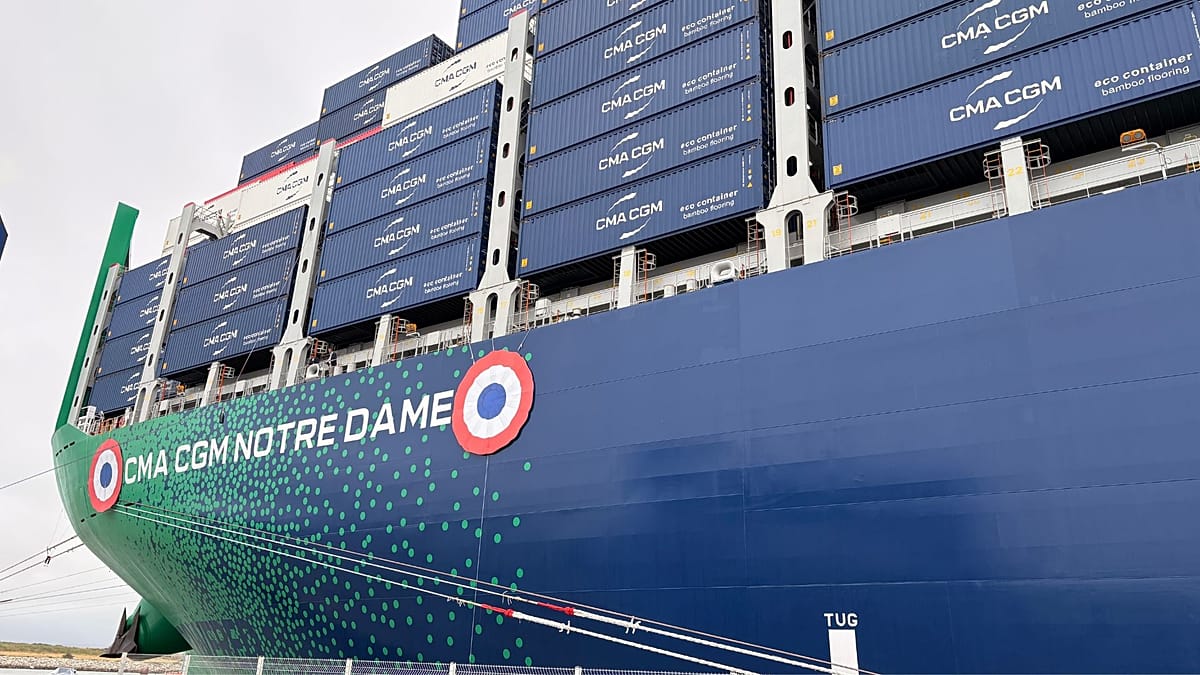
CMA CGM introduced a "Panama Canal Adjustment Factor" at $320 per container in July, announcing it would rise to $500 from September 10, as disclosed in a customer notice shared by Tradlinx on August 17.
This would be ordinary if the drought crisis justifying the charge persisted, but ShipFinex reported in February 2026 that Gatun Lake had refilled and the canal was running 38 transits per day at full draft. The fee persisted even after conditions normalized.
The Panama Canal Authority complicated the rationale for the surcharge by stating in mid-August, per an advisory cited by Tradlinx, that recent draft reductions would not reduce the number of daily transits. Ship passages remained available, with queueing driven by demand rather than capacity.
However, weather conditions worsened. gCaptain reported on August 21 that below-normal rainfall forced the Authority to cut Neopanamax slots to nine per day as of September 3, with Panamax slots dropping to 25 and later 23 through mid-September, and draft limits lowered further by October 1. As a result, two timelines diverged: carriers began charging for constrained transit before it materialized, while the canal’s slot reductions arrived weeks later.
Tradlinx documented that CMA CGM’s increase began July 25, MSC’s surcharge keyed to August, and Hapag-Lloyd’s took effect from September—all preceding or coinciding with the canal’s reductions, demonstrating that carriers moved before the canal.
The second mover, the Authority, confirmed the squeeze; the first mover, the carriers, captured margin.

The interests of the players are clear. Reuters, cited by gCaptain on October 25, reported that the Authority’s fiscal year, ending September, saw profits rise 9.5% to $3.45 billion despite dry conditions, reinforcing its campaign for a new reservoir as it continues to tighten restrictions. Meanwhile, CMA CGM, MSC, and Hapag-Lloyd aim to recoup auction costs and slower sailings without raising base rates. Asian shippers to the US East Coast seek predictability but instead get shifting surcharges, each triggered on a different carrier timetable. No line has disclosed how or when the surcharge would be removed if conditions improve.
This month’s trigger is too little rainfall, but the larger reality is structural: the canal consumes freshwater from a watershed that also supplies half of Panama’s drinking supply, dumping millions of gallons to the sea with each ship. The droughts of 2023 and 2024 made these stakes visible. Since then, carriers have learned that emergencies create pricing opportunities—and lessons like that are rarely unlearned.
The historical analogy is the Red Sea episode. After Houthi attacks diverted traffic in early 2024, war-risk surcharges layered onto rates and lingered even as the violence faded, because customers stopped challenging them. Surcharges created in crisis often settle as permanent charges. The counterexample is the Ever Given blockage in 2021, after which Suez Canal tolls reverted quickly. A finite event with a visible endpoint allowed charges to be rolled back. Drought is not finite, nor its end visible. With no definitive endpoint, shippers cannot easily demand refunds.
On August 13, the Shanghai–New York spot rate was $8,706 per forty-foot box. Drewry’s figures, relayed by Tradlinx on August 17, showed CMA CGM levying the $500 charge twice per forty-foot box, or nearly $1,000—11.5% of the spot rate—while Hapag-Lloyd’s equivalent was about 3%. Importers who bought on headline base rates are now learning that the fee line, not the base, sets the true landed cost.
Meanwhile, the canal itself is extracting scarcity rent directly. GCaptain reported August 21 that last-minute slot auctions reached $4.6 million for a single tanker, and that auctions, as of September 3, would split into categories (LNG, bulker, container, tanker) to better allocate scarcity. Drought is monetized all the way upstream.
Ultimately, US importers and consumers bear the cost. Tradlinx, citing canal statistics on August 17, showed that over half of transits serve US ports, and more than three-quarters of cargo by value, meaning American retailers face a water-driven surcharge set in Europe and collected in Panama, on a commodity—fresh water—that is not traded or hedged.
The test for this analysis will come if the surcharges outlast the drought. The Authority forecasts the wet season should again refill Gatun Lake, but no carrier has pledged to remove the charge when that happens. If December brings restored drafts, normal slot counts, and the $500 fee is still in place, the surcharge will have become part of standard pricing, not a crisis accommodation.
Alternatively, if the canal resumes 36-plus transits daily by November and carriers like MSC or Hapag-Lloyd drop their fee, it would show the charges were truly temporary, and any line maintaining a premium would risk losing customers. One way or another, the drought will end; the line item may not.