Europe set an end date for Russian gas and broke import records in 2024
European ports took nearly all Russia’s Arctic LNG output this year while a law bans the fuel starting in 2027.
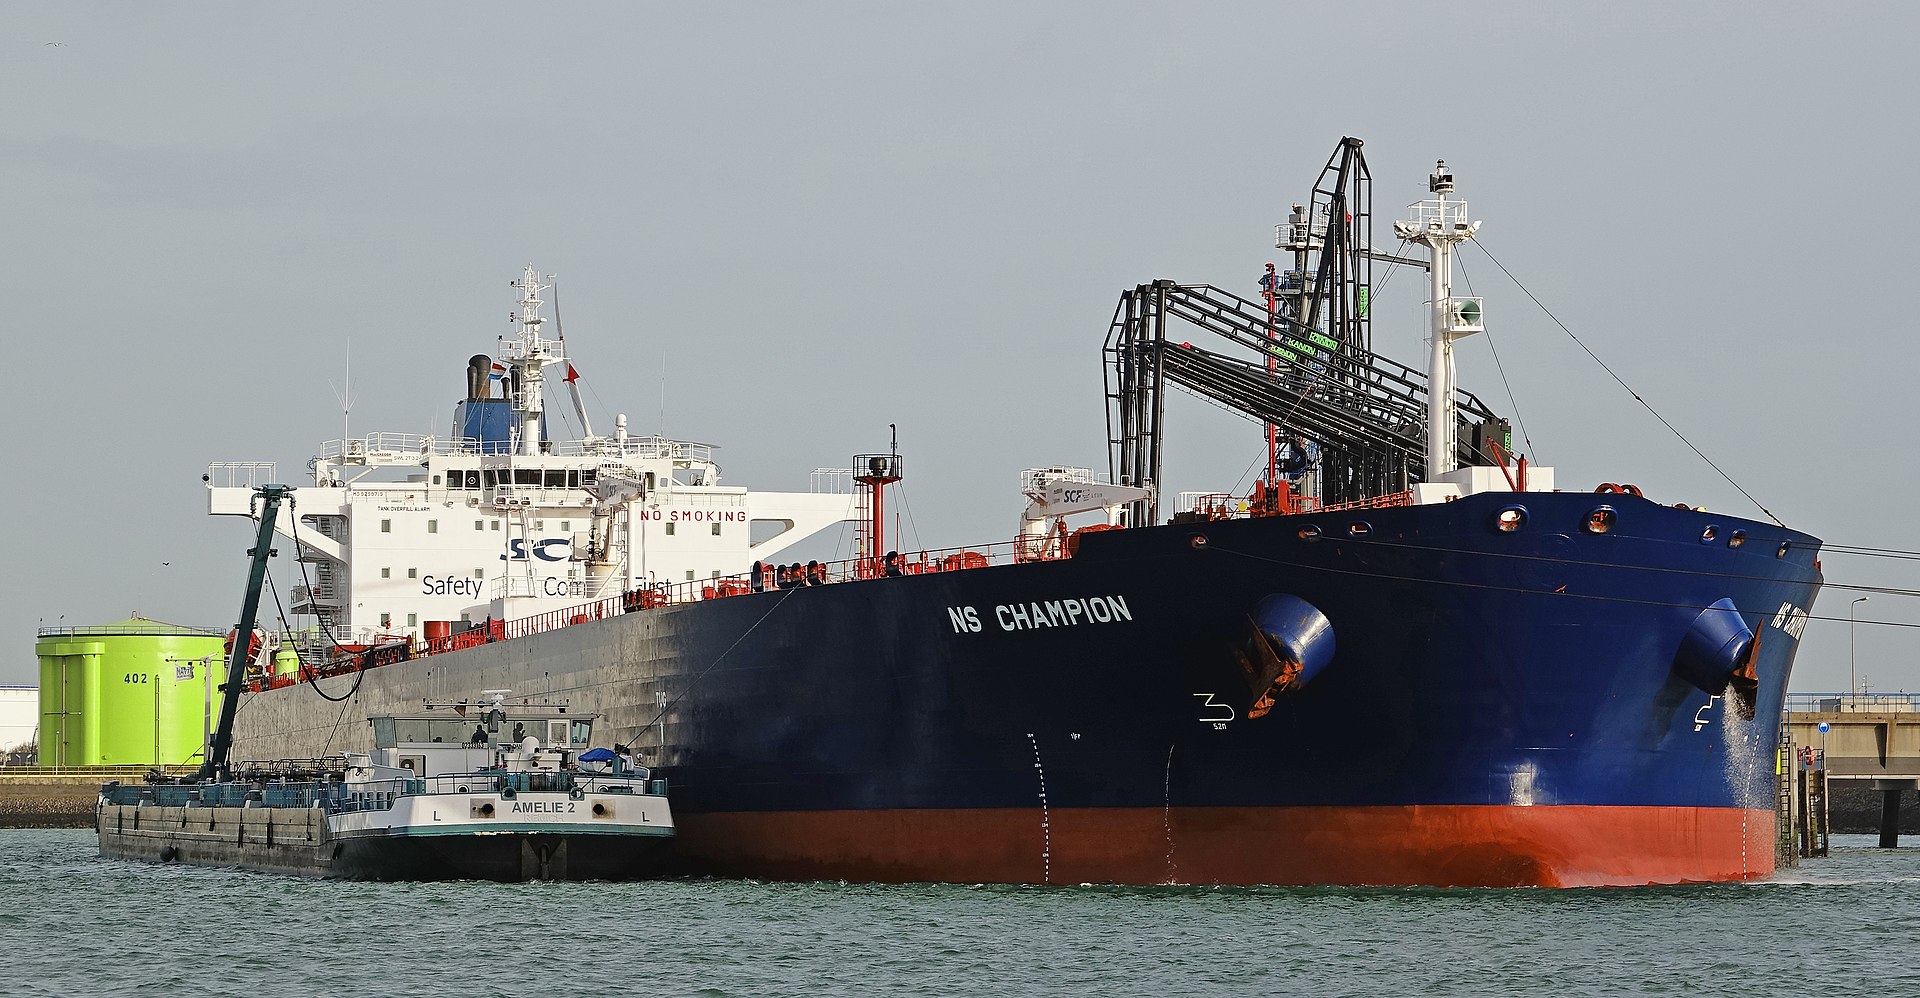
A law passed this year gives Russian gas a date of death in Europe: January 1, 2027. The first half of the phase-out already ran — spot and short-term LNG purchases ended April 25.
Then came the record books. In those same six months, EU ports took more liquefied gas from Russia than at any time before. European Gas Hub counted on July 15 that over 13 billion cubic meters came from the Yamal plant alone, roughly a fifth of everything the bloc imported. The continent banned the fuel and then bought it at a rate no year has matched.
One of those facts ends on January 1, 2027. The other is happening now, with the clock running.
The bill is precise. Urgewald's analysis of Kpler shipping data published July 13 found EU countries paid an estimated €5.96 billion for Yamal LNG between January and June, with 136 Russian Arctic cargoes delivered to EU ports out of just 140 shipped worldwide. Ninety-seven percent of Novatek's output had nowhere else to go. Marine Insight, citing Urgewald on July 14, described one cargo arriving every 1.3 days, about 55,000 tonnes daily. This is not leakage. It is the entire production line of Russia's flagship Arctic project pointed at the buyers who have legislated its death.
The buyers with contracts
Three countries did the buying. European Gas Hub’s July 15 tally showed Belgium, France and Spain together took around ninety percent of the EU's Russian LNG and drove eighty percent of the year-on-year growth. The reason sits in contracts signed long before the war. Bloomberg reported via gCaptain on November 18, 2024, that TotalEnergies of France, Spain's Naturgy and Germany's state-owned Securing Energy for Europe GmbH hold long-term offtake rights from Yamal, running until the end of 2026.
Some buyers are exercising upward quantity options and taking make-up volumes now, before the door shuts. A French energy ministry spokesperson told gCaptain/Bloomberg on November 18, 2024 that private companies import the fuel, and once it is regasified into the grid the molecules flow freely eastward.
European Gas Hub noted on July 15 that the rest of the world’s LNG got scarce because Middle East supply was disrupted through the summer Hormuz crisis, and European terminals competed for whatever floated. Meanwhile, the EU's own transshipment ban, in force since March 2025, makes it harder and costlier to forward Russian cargoes to Asia, so more of them terminate in Europe by default. The Northern Sea Route is only properly navigable from July to mid-November, which tilts Yamal’s summer economics toward the Atlantic rather than Asia. Every sanction Europe wrote made its own ports the path of least resistance.
The storage problem
The ban date is news; the storage problem is the story. European Gas Hub reported on August 19 that EU gas storage is on track for its lowest fill level since 2013, with current injection trends reaching only about seventy-three percent against an official target of eighty to ninety percent. Injections are down almost twenty percent, or 7.5 billion cubic meters, versus last year, because the market refuses to pay for storage.
Summer contracts have traded at a premium to winter ones all season, averaging minus €1.5 per MWh on the seasonal spread since April — you lose money buying gas now to sell it later. If trends hold, Europe enters November with 72 bcm underground, nineteen below the five-year average.
Europe cannot refill storage with Russian molecules after December, and this summer it chose to fill part of the gap with exactly those molecules while they were still legal. Come January, the same physical volume must come from the United States, Qatar or Norway, all of it priced off the same tight global market that TTF futures say will be tighter still.
European Gas Hub noted on July 22 that Dutch front-month prices were back above €60 per MWh as early as late July. The buyer of last resort in 2026 becomes the bidder without alternatives in 2027. Novatek knows this. So does whoever trades TTF call options for next winter.
Napoleon’s blockade
Napoleon's Continental Blockade of 1807 forbade Europe from trading with Britain, and for two years the continent officially complied while smuggling British cotton and colonial goods at spectacular premiums. The embargo raised the very prices that financed Britain’s war chest and corroded the alliances meant to enforce it. What differs today is enforcement.
The EU ban is written into law with dates and customs codes, not decreed from Paris, and there is no smuggling route for LNG, only contract dates everyone can read. What rhymes is the incentive: any buyer with a legal window buys cheap now and resells dear later, and the sanctioned seller earns hard currency from the coalition’s own members until the final hour.
Europe has done this before, for real. Oil and Gas 360 reported citing Council data in 2026 that after 2022 the bloc replaced most of its Russian pipeline gas within two years, and Russian gas is down to roughly thirteen percent of EU imports in 2025. Pipeline gas could be swapped because Norway laid on extra flows and global LNG kept expanding. But that adjustment happened when Europe still had storage capacity to spare and Asian demand was soft.
This time the exit lands in a year when inventories are tracking a thirteen-year low and every replacement molecule is bid for by Asia. The 2022 playbook assumed slack in the system. There is little left.
Households and industry across Germany, France and Italy pay through winter gas bills if a cold snap meets low storage; energy-intensive users — fertilizer plants, glass makers, chemicals — pay twice, once now in elevated summer prices and again in whatever volatility January brings. The profit side is equally direct. Urgewald’s July 13 count shows Novatek collected nearly six billion euros in six months from the bloc sanctioning it, American and Qatari exporters will collect the replacement premium after January, and traders holding winter TTF length collect the difference between the two.
If the read is right, Yamal cargoes keep landing at EU ports at or near the current cadence right up to late December — a final legal stockpile — while winter 2027 TTF contracts detach further above summer ones as buyers pre-pay for scarcity. That divergence is confirmation. What breaks the read: storage injections reversing sharply through September on falling prices, meaning mild weather and strong Norwegian flows closed the gap, or Brussels moving the full ban earlier than January 1, which would strand contracted cargoes and turn this story from irony into lawsuit.
Europe did not fail to quit Russian gas; it scheduled the quitting for after the filling season, then let the cheapest available molecules — Russia’s — do the filling.
Sanctions set the date. Incentives set the cargo manifest. Incentives have been winning every month of 2026, and the invoice arrives in January.